
 https://innews.az/uploads/news/2026-09/_innews_a346cd0c68c488ce056d9307e_o.jpg
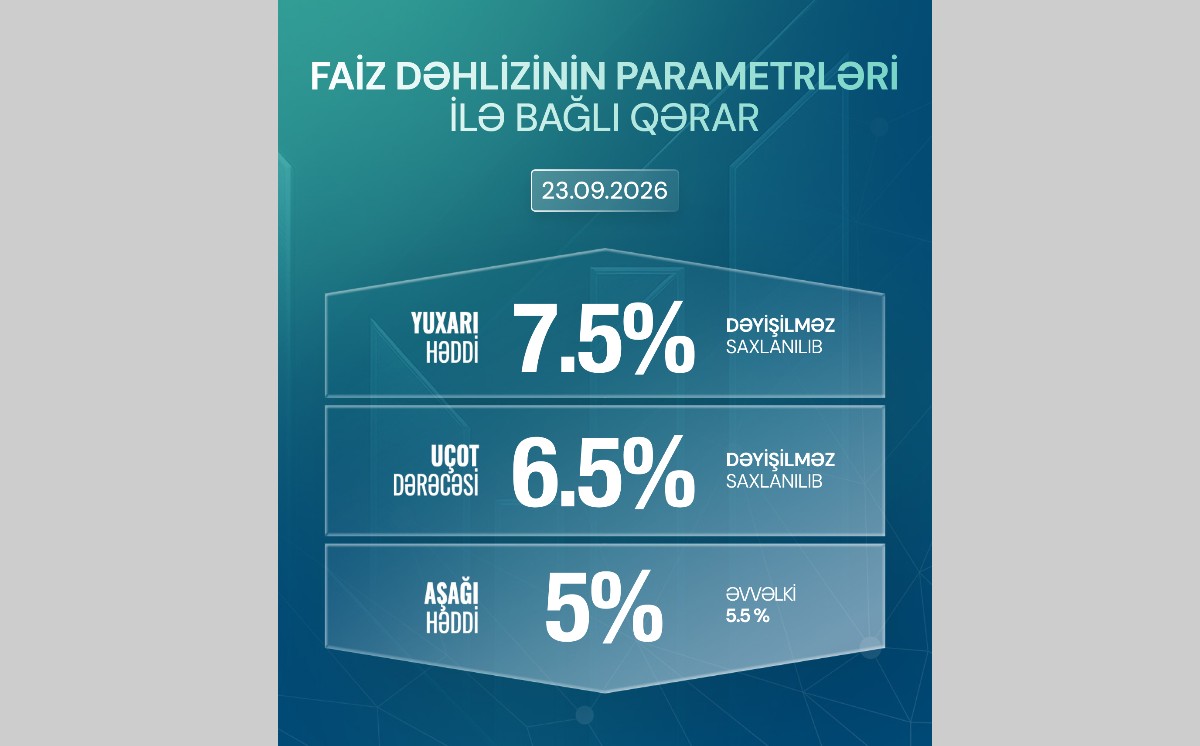
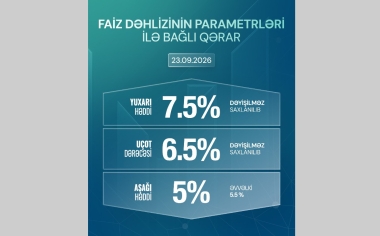
The Management Board of the Central Bank of the Republic of Azerbaijan decided to keep unchanged the refinancing rate at 6.5% and the ceiling at 7.5%, while the floor of the interest rate corridor was reduced by 0.5 pp to 5%. The decision was based on the dynamics of actual and forecasted inflation, foreign exchange market developments, the changes in banking sector liquidity and recent trends in the global monetary conditions.
The lowering of the floor of the interest rate corridor is aimed at promoting activity in the interbank money market amid excess liquidity in the banking sector. The widening of the interest rate corridor is expected to encourage more active interbank transactions by reducing Central Bank’s participation in the money market. At the same time, keeping the ceiling of the interest rate corridor and the refinancing rate unchanged is intended to support the stabilization of inflation expectations.
Annual inflation remains within the target band and is broadly evolving in line with the baseline forecast. In August 2026, twelve-month inflation stood at 5.7%, 0.1 pp lower than in July. Annual inflation was 7.2% for food, alcoholic beverages and tobacco products, 5.0% for paid services, and 3.7% for non-food goods. Annual core inflation stood at 5.1%. The Central Bank’s forecast that annual inflation will remain within the target band over the medium term remains unchanged.
Over the past period of current year, supply significantly prevailed over demand both in cash and cashless segments in the forex market. Over 8 months cash foreign currency purchases by exchange offices exceeded sales by $673M. Dollarization of resident individuals’ deposits decreased by 3.7 pp to 25.8% year-over-year in July 2026.
The Central Bank absorbed surplus in the forex market against the backdrop of a sharp decline in demand and an increase in supply. Over 8 months, FX reserves of the Central Bank increased by 32.9% to $15.3B, which is at the historic maximum level.
The external sector indicators remain favorable. According to the State Customs Committee, the trade surplus amounted to $10.4B in January-August 2026. Preliminary data show that, in January-August remittances surplus (the difference between inflows and outflows) amounted to $751M (year-over-year up by 74.1%). The Central Bank may revise upward its current account surplus forecast for the end of 2026, driven by higher global energy prices and positive trends in non-hydrocarbon exports of goods and services.
Excluding required reserves, the banking sector's structural liquidity surplus (the difference between the Central Bank's liabilities to banks and its claims on the banking system) reached AZN6.3B by the end of August 2026 (up by 2.2 times compared with December of the previous year). Against this backdrop, benchmark rates in the unsecured money market tended to decline slightly. The average daily AZIR rate stood at 6.39% in July 2026, 6.28% in August and 6.02% over the past period of September. Monetary policy tools are implemented taking into account financial market developments and banking system liquidity. The Central Bank primarily uses seven-day deposit operations to manage liquidity, which accounted for 70.8% of the sterilization portfolio under open market operations as of end-August. At the same time, the volume of the Central Bank’s note portfolio increased more than fourfold by the end of August compared with the end of the previous year.
There has been no significant change in the balance of risks to the inflation outlook since the previous meeting. Against the backdrop of global geopolitical uncertainty, the risk of higher energy and food prices, and the risk of these increases being passed through to domestic prices from major trading partners, remains significant. The extent of this pass-through will depend, among other factors, on the nominal effective exchange rate of the manat. Going forward, the extent to which the Central Bank’s inflation projections may need to be revised will depend primarily on the scale on which these risks materialize. Under the current fiscal and monetary policy conditions, domestic demand is not expected to foster inflationary pressures.
For the rest of the year, decisions on the parameters of the interest rate corridor will continue to be based on the inflation outlook, the dynamics of key macroeconomic indicators, forex market developments and banking sector liquidity. In view of uncertainties in the global environment and the intensity with which they may be transmitted to the domestic economy, the Central Bank will continue to review macroeconomic projections under several scenarios.
This decision will take effect as of 24 September 2026.
The schedule for the public communication of monetary policy decisions for 2026 has been revised. Accordingly, the date for the announcement of the next decision on the parameters of the interest rate corridor, as well as the date of the related press conference, was brought forward from 4 November 2026 to 29 October 2026. A meeting with experts is also scheduled to take place on the same day.
Ən son xəbərləri səhifəmizdən də izləyin